Marsh CFA Institute Global Pension Index 2026


An analysis of 55 pension systems around the world


Strengthening retirement income systems in an ageing world – New Zealand scores its best-ever result
Ageing populations, shifting workforce dynamics, and heightened geopolitical uncertainty are reshaping the retirement landscape. Now in its 18th edition, the Marsh CFA Institute Global Pension Index provides an established tool for benchmarking and comparing the world's retirement income systems, offering a structured framework to help decision-makers navigate the challenges ahead with greater clarity and confidence.
New Zealand’s retirement income system ranked 15th of 55 entrants in Marsh CFA Institute Global Pension Index 2026 (compared with 17th of 52 in 2025). New Zealand's overall index value rose to 71.4, up from 70.4 in 2025, maintaining its B grade. The result is underpinned by a strong integrity score, New Zealand ranks among the top-tier systems globally on this measure, alongside continued solid performance in adequacy and sustainability.
This year, the index benchmarks 55 retirement income systems worldwide with the addition of Dominican Republic, Kenya and Qatar. Together, these systems – covering 66% of the world’s population – spotlight both challenges and opportunities for policymakers.
How the index assesses retirement income systems
Systems are assessed across three pillars:
- Adequacy (40%)* – delivering meaningful retirement incomes today
- Sustainability (35%)* – remaining resilient for tomorrow
- Integrity (25%)* – earning the confidence of those who depend on it
* Percentages here correspond to the weighting given to the overall score.
Together, they capture the balance every system must strike. The report evaluates each system across more than 50 indicators to provide actionable insights.
2026 Deep Dive
Each year, the index features a deep dive into a topical issue. In 2026, the focus is on the impact of ageing populations on retirement income systems and how policy responses to demographic challenges can help develop sustainable policies in the long run.
Download the report to explore the 2026 findings and compare results across all benchmarked systems.
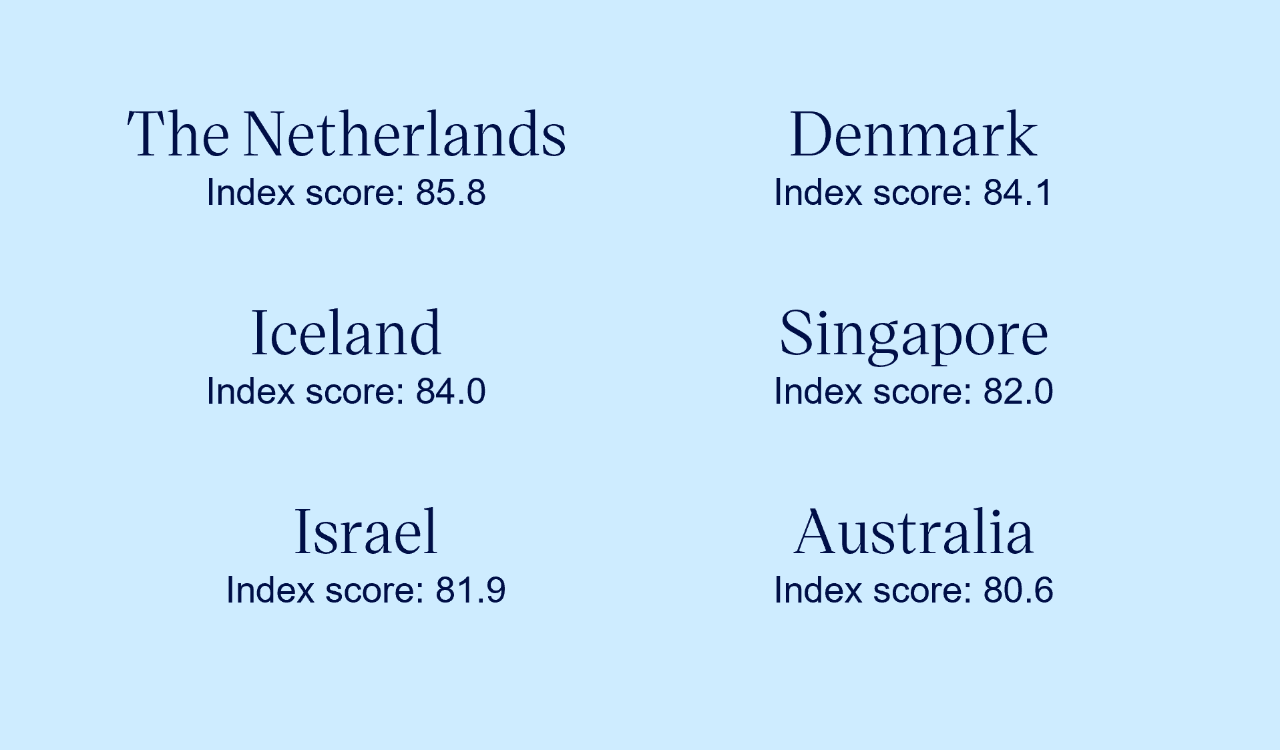
2026 A-grade retirement income systems
Netherlands
Denmark
Iceland
Singapore
Israel
Australia
Top 3 rated systems for each sub-index
-
Adequacy
How much do you get?
1. Kuwait
2. The Netherlands
3. France
33. New Zealand -
Sustainability
Can the system keep delivering?
1. Denmark
2. Iceland
3. The Netherlands
11. New Zealand -
Integrity
Can the system be trusted?
1. Finland
2. Norway
3. Singapore
14. New Zealand
People are living longer, work is changing, and the pressures on retirement income systems are growing. The question is no longer whether systems need to evolve, but how quickly and how effectively they can do so.
Lead author, Partner, Marsh, Investments and Retirement
Overall grade for each retirement income system

 MCGPI A Grades
- China C+ (60.6 ▲)
- Hong Kong SAR B (71.2 ▲)
- India D (46.8 ▲)
- Indonesia C (50.7 ▼)
- Japan C (58.0 ▲)
- Korea (South) C (56.4 ▲)
- Malaysia C+ (61.1 ▲)
- Philippines D (49.2 ▲)
- Singapore A (82.0 ▲)
- Taiwan C (59.7 ▲)
- Thailand C (52.2 ▲)
- Vietnam C (54.6 ▲)

- Austria C (56.9 ▲)
- Belgium B (68.1 ▼)
- Croatia B (66.1 ▼)
- Denmark A (84.1 ▲)
- Finland B+ (77.6 ▲)
- France B (70.3 =)
- Germany B (67.9 ▲)
- Iceland A (84.0 =)
- Ireland B (69.7 ▲)
- Italy C (57.4 ▲)
- Netherlands A (85.8 ▲)
- Norway B+ (77.0 ▲)
- Poland C (58.4 ▲)
- Portugal B (67.3 ▼)
- Spain C+ (63.3 ▼)
- Sweden B+ (78.8 ▲)
- Switzerland B (73.6 ▲)
- United Kingdom B (71.6 ▼)

- Botswana C (57.0 ▼)
- Israel A (81.9 ▲)
- Kazakhstan C+ (64.8 ▼)
- Kenya C (53.1)
- Kuwait B (72.9 ▲)
- Namibia C (57.5 ▼)
- Oman B (69.9 ▲)
- Qatar B (66.0)
- Saudi Arabia B (73.2 ▲)
- South Africa C (50.4 ▼)
- Türkiye D (46.6 ▼)
- United Arab Emirates B (70.0 ▲)

- Argentina D (43.7 ▼)
- Brazil C (57.0 ▲)
- Chile B+ (79.2 ▲)
- Colombia C+ (63.3 ▲)
- Dominican Republic C+ (61.4)
- Mexico B (71.2 ▲)
- Panama C+ (62.0 ▲)
- Peru C (55.7 ▲)
- Uruguay B (69.7 ▼)

- Australia A (80.6 ▲)
- New Zealand B (71.4 ▲)

- Canada B (70.6 ▲)
- United States of America C+ (61.6 ▲)
The impact of ageing populations on retirement income systems
Many nations are facing an ageing population due to falling birth rates and increasing life expectancies. These demographic changes have profound long-term implications for retirement income systems:
- Potentially increased costs of pension provision as individuals live longer,
- Funding pressures as working age populations proportionately decrease,
- The need for more flexible pension designs to accommodate phased retirement and non-traditional employment,
- Intergenerational tensions as adequacy and sustainability of systems are reviewed,
- Shifts in investment strategies as a greater proportion of the US$70 trillion in global pension fund assets moves toward defensive positioning.
Policymakers who recognize these demographic consequences have a window of opportunity to implement evidence-based policy responses, which we explore in our report.
The central insight is straightforward: demography is our destiny, but policy responses are choices. While demographic changes are inevitable, the path forward is not predetermined. Those systems that consider and address the demographic consequences today will be much better positioned to develop sustainable retirement income policies that provide adequate and equitable retirement security for generations to come. The evidence shows that with clear objectives, thoughtful funding, and flexible design, leading pension systems can remain resilient.
In New Zealand, these dynamics are already playing out. The Index points to the alignment between KiwiSaver eligibility and the NZ Super age, household savings levels, as well as KiwiSaver's focus on delivering retirement income as factors likely to influence the system's future results.
The Index makes clear that without meaningful reform – clearer system objectives, stronger funding, and more flexible product design – too many people will reach retirement without the security they need.
Managing Director of the Research & Policy Center, CFA Institute
See also: Supplementary report
Meet our lead author and contributors
Before accessing this website you must read and accept the following terms and legal notices.
You are about to enter a website intended for sophisticated, institutional investors based in New Zealand. The information contained herein is only intended for investors who are wholesale investors for the purposes of the Financial Markets Conduct Act 2013. Any person unable to accept these terms and conditions should not proceed any further.
In New Zealand, Mercer’s Outsourced Chief Investment Officer, Delegated Solutions and other Investment Services are delivered by Mercer (N.Z.) Limited, the manager of the Mercer Investment Trusts New Zealand and the Mercer Wholesale Funds.
Information about Mercer strategies and solutions is provided for informational purposes only and does not constitute, and should not be construed as, an offer to sell, or a solicitation of an offer to buy, any securities, or an offer, invitation or solicitation of any specific products or the investment management services of Mercer, or an offer or invitation to enter into any portfolio management mandate with Mercer. None of the content on Mercer.Com should be considered as regulated financial advice. No actions should be taken based on this content without first obtaining professional advice. Mercer makes no representation, and it should not be assumed, that past investment performance is an indication of future results. Moreover, wherever there is the potential for profit there is also the possibility of loss. Past performance does not guarantee future results. The value of investments can go down as well as up, so you could get back less than you invest.
Mercer reserves the right to suspend or withdraw access to any page(s) included on this Website without notice at any time and accepts no liability if, for any reason, these pages are unavailable at any time or for any period. The solutions, products and services described in these pages are not available in all jurisdictions.