Marsh CFA Institute Global Pension Index 2026
An analysis of 55 pension systems around the world


Strengthening retirement income systems in an aging world
Aging populations, shifting workforce dynamics, and heightened geopolitical uncertainty are reshaping the retirement landscape. Now in its 18th edition, the Marsh CFA Institute Global Pension Index provides an established tool for benchmarking and comparing the world's retirement income systems, offering a structured framework to help decision-makers navigate the challenges ahead with greater clarity and confidence.
This year, the index benchmarks 55 pension systems worldwide with the addition of Dominican Republic, Kenya and Qatar – covering 66% of the world’s population – spotlighting both challenges and opportunities for policymakers.
Systems are assessed across three pillars:
-
Adequacy (40%)*
Delivering meaningful retirement incomes today -
Sustainability (35%)*
Remaining resilient for tomorrow -
Integrity (25%)*
Earning the confidence of those who depend on it
Together, they capture the balance every pension system must strike. The report evaluates each system across more than 50 indicators to provide actionable insights.
Each year, the index also features a deep dive into a topical issue. In 2026, the focus is on the impact of aging populations on pension systems and how policy responses to demography challenges can help develop sustainable retirement income policies in the long run.
Browse through the report below to discover more about the analysis and each benchmarked retirement income system.
This year’s A-grade retirement income systems

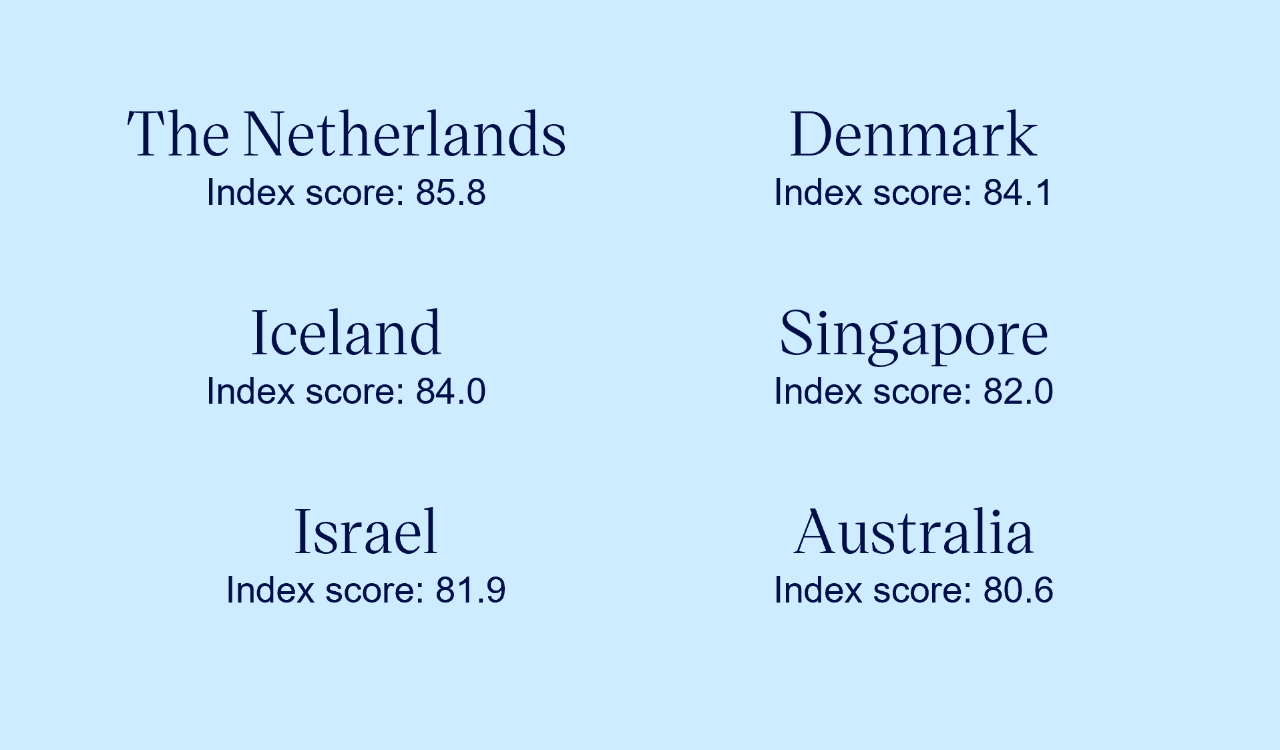 MCGPI A Grades
Top 3 rated systems for each sub-index
-
Adequacy
How much do you get?
1. Kuwait
2. The Netherlands
3. France -
Sustainability
Can the system keep delivering?
1. Denmark
2. Iceland
3. The Netherlands -
Integrity
Can the system be trusted?
1. Finland
2. Norway
3. Singapore
People are living longer, work is changing, and the pressures on retirement income systems are growing. The question is no longer whether systems need to evolve, but how quickly and how effectively they can do so.
Lead author, Partner, Marsh, Investments and Retirement
View the full 2026 report
Overall grade for each retirement income system

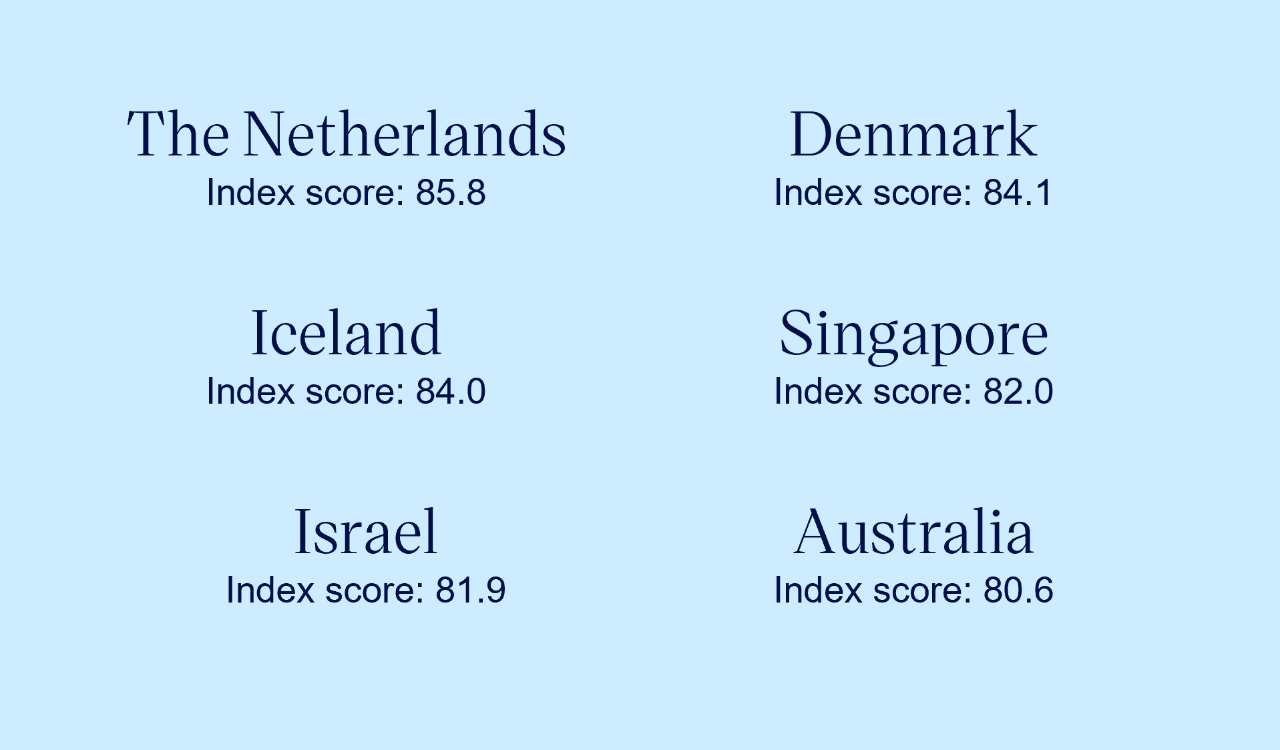 MCGPI A Grades
- China C+ (60.6 ▲)
- Hong Kong SAR B (71.2 ▲)
- India D (46.8 ▲)
- Indonesia C (50.7 ▼)
- Japan C (58.0 ▲)
- Korea (South) C (56.4 ▲)
- Malaysia C+ (61.1 ▲)
- Philippines D (49.2 ▲)
- Singapore A (82.0 ▲)
- Taiwan C (59.7 ▲)
- Thailand C (52.2 ▲)
- Vietnam C (54.6 ▲)

- Austria C (56.9 ▲)
- Belgium B (68.1 ▼)
- Croatia B (66.1 ▼)
- Denmark A (84.1 ▲)
- Finland B+ (77.6 ▲)
- France B (70.3 =)
- Germany B (67.9 ▲)
- Iceland A (84.0 =)
- Ireland B (69.7 ▲)
- Italy C (57.4 ▲)
- Netherlands A (85.8 ▲)
- Norway B+ (77.0 ▲)
- Poland C (58.4 ▲)
- Portugal B (67.3 ▼)
- Spain C+ (63.3 ▼)
- Sweden B+ (78.8 ▲)
- Switzerland B (73.6 ▲)
- United Kingdom B (71.6 ▼)

- Botswana C (57.0 ▼)
- Israel A (81.9 ▲)
- Kazakhstan C+ (64.8 ▼)
- Kenya C (53.1)
- Kuwait B (72.9 ▲)
- Namibia C (57.5 ▼)
- Oman B (69.9 ▲)
- Qatar B (66.0)
- Saudi Arabia B (73.2 ▲)
- South Africa C (50.4 ▼)
- Türkiye D (46.6 ▼)
- United Arab Emirates B (70.0 ▲)

- Argentina D (43.7 ▼)
- Brazil C (57.0 ▲)
- Chile B+ (79.2 ▲)
- Colombia C+ (63.3 ▲)
- Dominican Republic C+ (61.4)
- Mexico B (71.2 ▲)
- Panama C+ (62.0 ▲)
- Peru C (55.7 ▲)
- Uruguay B (69.7 ▼)

- Australia A (80.6 ▲)
- New Zealand B (71.4 ▲)

- Canada B (70.6 ▲)
- United States of America C+ (61.6 ▲)
A brief review of each system
The impact of aging populations on pension systems
Many nations are facing an aging population due to falling birth rates and increasing life expectancies. These demographic changes have profound long-term implications for pension systems:
- Potentially increased costs of pension provision as individuals live longer,
- Funding pressures as working age populations proportionately decrease,
- The need for more flexible pension designs to accommodate phased retirement and non-traditional employment,
- Intergenerational tensions as adequacy and sustainability of systems are reviewed,
- Shifts in pension fund investment strategies as a greater proportion of the US$70 trillion in global pension fund assets moves toward defensive positioning.
Policymakers who recognize these demographic consequences have a window of opportunity to implement evidence-based policy responses, which we detail in our report.
The central insight is straightforward: demography is our destiny, but policy responses are choices. While demographic changes are inevitable, the path forward is not predetermined.
Retirement systems differ across markets, but all face the same long-term challenge: Delivering reliable income as demographics shift and markets change.
Managing Director, CFA Institute Research and Policy Center
See also: Supplementary report
Meet our lead author and contributors
References to Mercer shall be construed to include MMC Financial Company (Mercer) and/or its associated companies.
© 2023 MMC Financial Company. All rights reserved.
This content may not be modified, sold or otherwise provided, in whole or in part, to any other person or entity without Mercer's prior written permission.
Mercer does not provide tax or legal advice. You should contact your tax advisor, accountant and/or attorney before making any decisions with tax or legal implications.
This does not constitute an offer to purchase or sell any securities.
The findings, ratings and/or opinions expressed herein are the intellectual property of Mercer and are subject to change without notice. They are not intended to convey any guarantees as to the future performance of the investment products, asset classes or capital markets discussed.
This does not contain investment advice relating to your particular circumstances. No investment decision should be made based on this information without first obtaining appropriate professional advice and considering your circumstances. Mercer provides recommendations based on the particular client's circumstances, investment objectives and needs. As such, investment results will vary and actual results may differ materially.
Past performance is no guarantee of future results. The value of investments can go down as well as up, and you may not get back the amount you have invested. Investments denominated in a foreign currency will fluctuate with the value of the currency. Certain investments, such as securities issued by small capitalization, foreign and emerging market issuers, real property, and illiquid, leveraged or high-yield funds, carry additional risks that should be considered before choosing an investment manager or making an investment decision.
Information contained herein may have been obtained from a range of third party sources. While the information is believed to be reliable, Mercer has not sought to verify it independently. As such, Mercer makes no representations or warranties as to the accuracy of the information presented and takes no responsibility or liability (including for indirect, consequential, or incidental damages) for any error, omission or inaccuracy in the data supplied by any third party.
For the most recent approved ratings of an investment strategy, and a fuller explanation of their meanings, contact your Mercer representative.
Mercer universes: Mercer’s universes are intended to provide collective samples of strategies that best allow for robust peer group comparisons over a chosen timeframe. Mercer does not assert that the peer groups are wholly representative of and applicable to all strategies available to investors.
Please see the following link for information on investment management index definitions.
Not all services mentioned are available in all jurisdictions. Please contact your Mercer representative for more information.
In the Kingdom of Saudi Arabia, Mercer’s Investment Services are delivered by MMC Financial Company (“MMCFC”). MMCFC is regulated by the Capital Market Authority (CMA), License No. 20-22238. MMCFC is incorporated in the Kingdom of Saudi Arabia, Commercial License No. 431210240571.
For the conflict of interest statement of Mercer Investments, of which MMCFC is a part, contact your Mercer representative or see https://www.mercer.com/conflictsofinterest.